
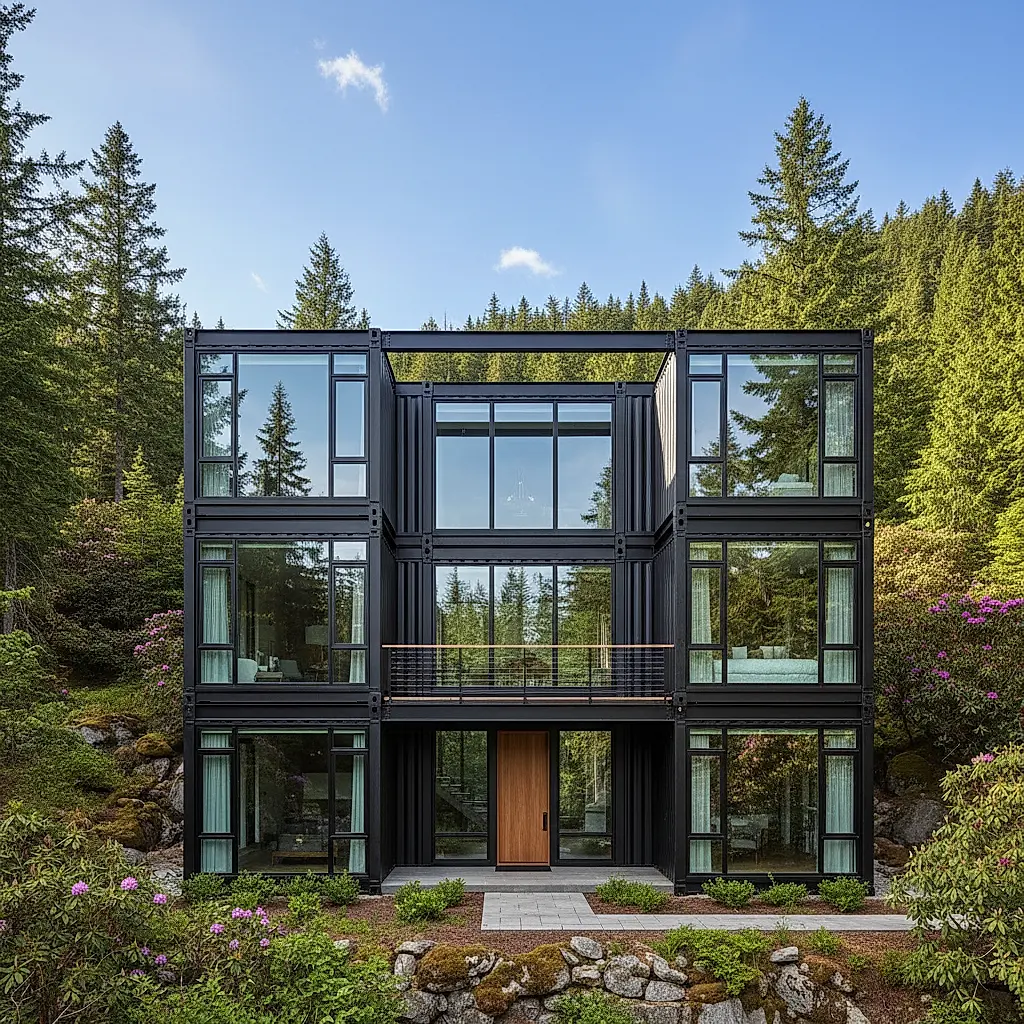
Insuring a container home involves unique questions. Learn how to talk to insurers, document modifications, and plan coverage without guesswork.
Why container home insurance needs a different conversation
A standard homeowners policy is written with conventional stick-built construction in mind. When you live in a structure built from one or more shipping containers, the insurance conversation changes. Carriers may see the home as a modified structure, an unconventional build, or a hybrid of steel shell and framed interior. That does not automatically make it uninsurable, but it usually means you should expect more questions and more documentation.
This article is a planning guide, not a quote. Insurance rules, carrier appetites, and state regulations vary and change. Nothing here replaces a conversation with a licensed agent in your state. Use it to organize your information so that conversation goes faster and produces fewer surprises.
What insurers tend to ask about a container home
When you request a quote, an agent will typically want to understand the risk they are being asked to cover. For a container-based dwelling, that often means explaining the structure itself, how it was built, and how it is used.
Structure and provenance
Be ready to describe where the containers came from, whether they were new or used, and whether they carry a CSC plate. The CSC plate is a safety approval plate used in international transport, and it can help document a container's history. Insurers may or may not care about it, but having the information available is useful. For exact specifications, refer to the individual listing and the plate on the unit itself.
Modifications and systems
Most container homes are not raw containers. They have cut openings, welded framing, insulation, interior finishes, plumbing, electrical, and HVAC. Each of those modifications can affect how a carrier evaluates the home. Keep a clear record of who performed the work and what was installed.
Occupancy and use
Is this your primary residence, a vacation home, a rental, or a workshop with living space? Occupancy is one of the biggest factors in how a policy is priced and whether a carrier will write it at all.
Location and site access
Rural sites, off-grid setups, and properties far from a fire station can raise questions. So can access roads, gates, and whether emergency vehicles can reach the home. Confirm site access and delivery requirements with the Newport team before you finalize a site plan, and share the same details with your agent.
Types of coverage to discuss with your agent
Container homes can raise the same core coverage questions as any home, but the answers may differ. Ask your agent to walk through each of these categories rather than assuming a standard package fits.
- Dwelling or structure coverage: What is covered, and how is replacement cost determined for a steel-shell home with custom interior work?
- Personal property: Does the policy cover your belongings inside the home, and are there sublimits for tools, electronics, or equipment stored on site?
- Liability: If someone is injured on your property, what does the policy pay, and are there exclusions related to construction features or outbuildings?
- Loss of use: If the home becomes uninhabitable after a covered loss, what does the policy provide for temporary housing?
- Other structures: Sheds, container workshops, carports, and detached units are often handled separately. Ask how each is classified.
- Construction phase coverage: If you are still building, ask whether you need a builder's risk policy and when it should convert to a permanent policy.
Replacement cost versus actual cash value
Replacement cost coverage generally pays to rebuild or repair with materials of similar kind and quality. Actual cash value generally pays less, reflecting depreciation. For a container home with custom fabrication, replacement cost may be the more meaningful option, but it can also be harder to underwrite. Ask your agent how each basis would apply to your specific build.
Liability coverage for a container home
Liability coverage is about injuries and property damage you may be responsible for. A container home can raise questions about stairs, decks, lofts, and any detached container structures on the property. If you plan to host guests, run a short-term rental, or operate a business from the property, tell your agent. Those uses often require endorsements or a different policy form.
Documenting your build before you need a claim
Good documentation helps at quote time and at claim time. It also reduces the chance that a carrier declines a claim because a modification was never disclosed.
Keep a build file
- Photos of the containers before, during, and after modification
- Receipts and contracts for welding, framing, insulation, electrical, plumbing, and HVAC
- Engineering or design documents you already have
- Permits and inspection records from your local authority
- A simple floor plan showing rooms, exits, and utility locations
- Serial numbers or identifying information for major systems
Update the file as you change the home
Additions, new decks, solar arrays, wood stoves, and accessory containers can all change your risk profile. A quick email to your agent when something changes is easier than sorting it out after a loss.
Be honest about DIY work
Many container homes involve some owner-built elements. Insurers may ask who did the electrical, plumbing, and structural work. If you did some of it yourself, say so. Undisclosed DIY work is a common reason claims get complicated.
How to shop for coverage without wasting time
Not every carrier writes container homes, and not every agent has experience with them. A little preparation can save hours.
Start with agents who understand alternative construction
Ask directly whether the agency has placed coverage for container homes, barndominiums, or other alternative construction. If the answer is no, ask for a referral rather than pushing forward.
Prepare a one-page summary
Include the home's location, approximate size, year completed, construction details, occupancy, and any business use. Note that approximate nominal container dimensions, such as length and width, and whether the unit is standard or high cube, can be part of that summary. For exact figures, refer to the individual listing and the CSC plate.
Expect a range, not a single number
Quotes can vary widely based on state, carrier, credit history, claims history, and the details of your build. Treat any figure you hear as specific to that quote, not as a market benchmark.
Ask what would improve your options
Sometimes a wind mitigation feature, a documented professional inspection, or a change in how an outbuilding is classified can open up more carriers. Ask your agent what would help.
Common friction points and how to plan around them
The home is not finished yet
If you are mid-build, you may need construction-phase coverage before a permanent policy is available. Ask when the transition should happen and what documentation the carrier will want at that point.
The home is off-grid or rural
Water sources, power sources, and distance from fire protection can all affect underwriting. Be ready to explain how the home operates and what fire mitigation exists on the property.
Part of the property is used for business
Storing inventory, running a shop, or renting the home can change how a carrier views the risk. Disclose it early.
You are not sure what counts as a modification
When in doubt, disclose. It is better to answer an extra question at quote time than to discover an exclusion after a loss.
Frequently Asked Questions
Is a container home harder to insure than a traditional home?
It can be, but difficulty varies by state, carrier, and how the home was built. Some carriers are comfortable with alternative construction; others are not. The key is finding an agent who has placed this type of coverage before and being ready to document your build clearly.
Does a CSC plate affect my insurance?
A CSC plate is a safety approval plate used in international transport. It can help document a container's history, but whether an insurer considers it is up to that carrier. Refer to the plate on your unit and the individual listing for exact details.
Do I need a special policy for a container home?
Not necessarily. Some homes can be covered under a standard dwelling form with endorsements, while others need a specialty carrier. Your agent will determine which forms are available in your state for your specific build and occupancy.
What if I use part of the property as a business?
Tell your agent. Business use, storage, and short-term rentals often require different forms or endorsements. Disclosing it early gives you more options than discovering a coverage gap later.
Can I get coverage while I am still building?
Construction-phase coverage, sometimes called builder's risk, is often used before a permanent policy is issued. Ask your agent when that transition should happen and what documentation will be needed.
Next steps for your container home project
Insurance is one part of a larger planning process. Before you commit to a build, confirm the details of the container itself, the site, and the delivery plan. Start by reviewing available units at our shop, then reach out to the Newport team at our contact page to confirm listing details, availability, pricing, site access, and delivery requirements. For insurance specifics, work with a licensed agent in your state who can review your build documents and explain your actual options.
Plan the next step
Confirm the container and the delivery plan.
Browse current listings, then speak with the Newport team to verify the unit, total pricing, site access, and delivery requirements before payment.