
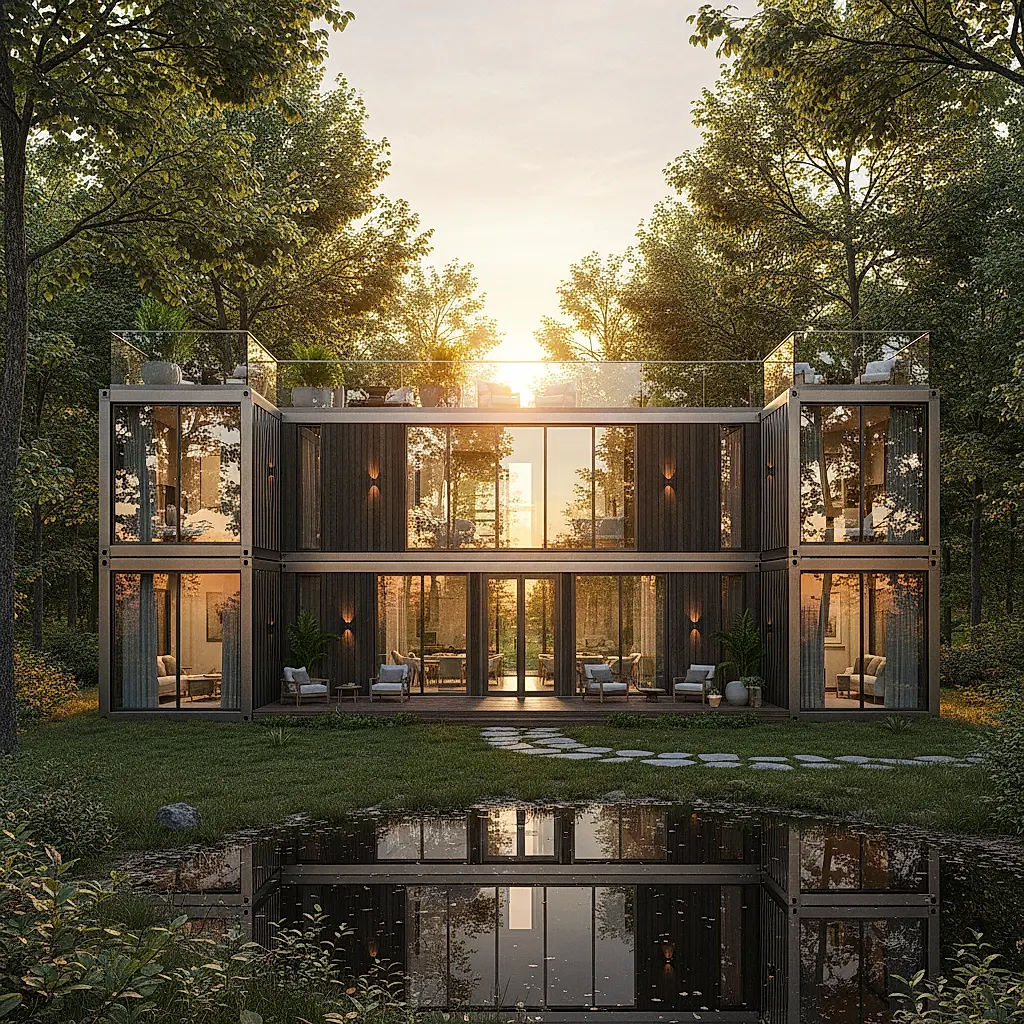
Financing a container home is possible, but it works differently from a standard mortgage. Learn how lenders view container builds, what to prepare, and how to plan with confidence.
Financing a home built from shipping containers is possible, but it rarely follows the same path as a conventional house purchase. Lenders, appraisers, and insurers look at container homes through a different lens, and understanding that lens early can save you months of frustration. This guide walks through how container home financing generally works, what lenders tend to ask, and how to prepare before you buy your containers.
Why Container Home Financing Is Different
A container home is not just a house with an unusual exterior. It is often classified as a modular or manufactured structure, or as a site-built home using alternative materials, depending on how it is designed, permitted, and affixed to the land. That classification drives nearly every financing decision.
Lenders Care About Four Things
Most lenders evaluating a container home want clarity on:
- Foundation and permanence. Is the home on a permanent foundation, or is it treated as a movable structure? Permanent foundations generally open more loan options.
- Permits and inspections. Has the local building authority approved the plans, and will the home be inspected at standard construction milestones?
- Appraisal support. Can an appraiser find comparable sales? Container homes are less common, so comparable data may be thin.
- Insurability. Can you obtain standard homeowners insurance? If not, financing usually stalls.
None of these are automatic deal-breakers. They are simply the questions that shape which loan programs are realistic for your project.
Common Financing Paths
Depending on your situation, you may encounter:
- Construction-to-permanent loans. Funds are released in draws as the build progresses, then convert to a standard mortgage at completion.
- Traditional mortgages on completed homes. Possible when the home is permanently affixed, permitted, and appraised with usable comparables.
- Manufactured or modular home loans. Sometimes applicable when the home meets specific structural and certification standards.
- Personal or specialty loans. Often used for smaller projects or when the home will not be permanently affixed.
- Cash or staged cash purchases. Some buyers purchase containers and build in phases to reduce financing complexity.
Availability varies by lender, state, and project type. Confirm current program details directly with lenders rather than relying on general guidance.
How to Prepare Before You Apply
Preparation is where container home projects are won or lost. Lenders respond well to organized, documented plans.
Build a Documentation Package
Gather and keep copies of:
- Site plan and survey
- Engineered drawings or stamped plans
- Local permits and approvals
- Contractor bids or a detailed construction budget
- A realistic timeline with contingency
- Insurance quotes or a letter of intent from an insurer
- Your own financial documents: income, assets, and credit history
Talk to Lenders Early
Do not wait until you have containers on site. Speak with several lenders, including local banks and credit unions that know your market. Ask specifically whether they have financed container or modular homes before. A lender who has done it once is far easier to work with than one who has not.
Ask About Appraisal Strategy
The appraisal is frequently the hardest step. Ask lenders how they handle appraisals for unique homes and whether they will consider alternative valuation methods. You may also want to ask whether a cost-based appraisal or a review of modular comparables is acceptable in your area.
Understanding Appraisals for Container Homes
An appraisal is an opinion of value supported by evidence. When a home is uncommon, the evidence is harder to assemble.
What Appraisers Look For
- Recent sales of similar homes, including modular and alternative-material homes
- Construction cost data, if comparable sales are limited
- Site value and land improvements
- Quality of finishes and systems
- Whether the home conforms to the neighborhood
How to Support the Process
You can help by providing:
- A complete set of plans and specifications
- A line-item construction budget
- Documentation of permits and inspections
- Photos at each construction stage
- Information about the container specifications from your supplier, including the CSC plate details where applicable
Appraisal outcomes are never guaranteed. Discuss expectations with your lender before you commit to a loan application fee.
Insurance, Zoning, and Local Rules
Financing rarely happens without insurance, and insurance rarely happens without a home that meets local requirements.
Insurance Considerations
Insurers may ask whether the structure is permanently affixed, how it is classified, and whether it meets applicable building codes. Some carriers are comfortable with container homes; others are not. Get quotes early and keep written confirmation.
Zoning and Code
Local zoning and building departments determine whether a container structure is allowed on your property and under what conditions. Requirements vary widely between jurisdictions. Contact your local authority for the exact rules that apply to your site. Do not assume that a particular container size or design will simplify or avoid permitting.
Delivery and Site Access
Financing timelines often depend on construction milestones, which in turn depend on delivery. Confirm site access, unloading requirements, and scheduling with the Newport team before you finalize your loan draw schedule. For containers themselves, you can browse current options at our shop.
Building a Realistic Budget
A container home budget has the same major categories as any home, plus a few container-specific ones.
Typical Budget Categories
- Land and site work
- Containers and modifications
- Foundation and structural work
- Framing, insulation, and finishes
- Electrical, plumbing, and HVAC
- Permits, engineering, and inspections
- Delivery and placement
- Contingency
Where Costs Surprise People
- Modifications. Cutting, reinforcing, and finishing containers is skilled work.
- Insulation and moisture control. Steel behaves differently from wood; proper detailing matters.
- Engineering. Stamped plans and structural reviews add cost but often unlock financing.
- Contingency. Unique builds tend to encounter unique problems.
Keep a contingency line and revisit it as the project progresses. For current pricing and availability on containers, check individual listings and confirm details with our team.
Frequently Asked Questions
Can you get a mortgage on a shipping container home?
Sometimes. It depends on whether the home is permanently affixed, permitted, inspected, insurable, and appraisable in your market. Many buyers use construction-to-permanent loans or specialty lenders. Requirements vary, so confirm directly with lenders and your local building authority.
How do appraisers value a container home?
Appraisers look for comparable sales first. When those are limited, they may rely on construction cost data, site value, and the quality of the finished home. Providing complete plans, budgets, and inspection records can help, but the final valuation is the appraiser's professional judgment.
Is a container home considered a manufactured home?
Not always. Classification depends on how the home is built, certified, and affixed. Some container homes are treated as site-built structures; others may fall under modular or manufactured categories. Your local building department and lender will determine how your project is classified.
What should I do before applying for financing?
Assemble your plans, permits, budget, timeline, insurance quotes, and personal financial documents. Speak with multiple lenders early, including local institutions. Confirm site access and delivery logistics with the Newport team so your construction schedule is realistic.
Do container homes cost less to finance?
There is no universal answer. Financing costs depend on the loan program, lender risk assessment, appraisal outcome, and your financial profile. Compare offers and ask each lender to explain fees and terms in writing.
Next Steps for Your Container Home Project
Start with clarity on the container itself, then build your financing plan around it. Browse available units and confirm specifications, condition, and availability on each listing at our shop. When you are ready to discuss delivery, site access, or documentation you may need for lenders, reach out through our contact page. The Newport team can help you confirm listing details and coordinate the practical steps, while your lender and local officials guide the financing and permitting decisions that are specific to your project.
Plan the next step
Confirm the container and the delivery plan.
Browse current listings, then speak with the Newport team to verify the unit, total pricing, site access, and delivery requirements before payment.